Compression Comes Before Expansion on NQ
A dead, narrow day feels like nothing is happening. It is often the setup for the opposite. We tested it on NQ.
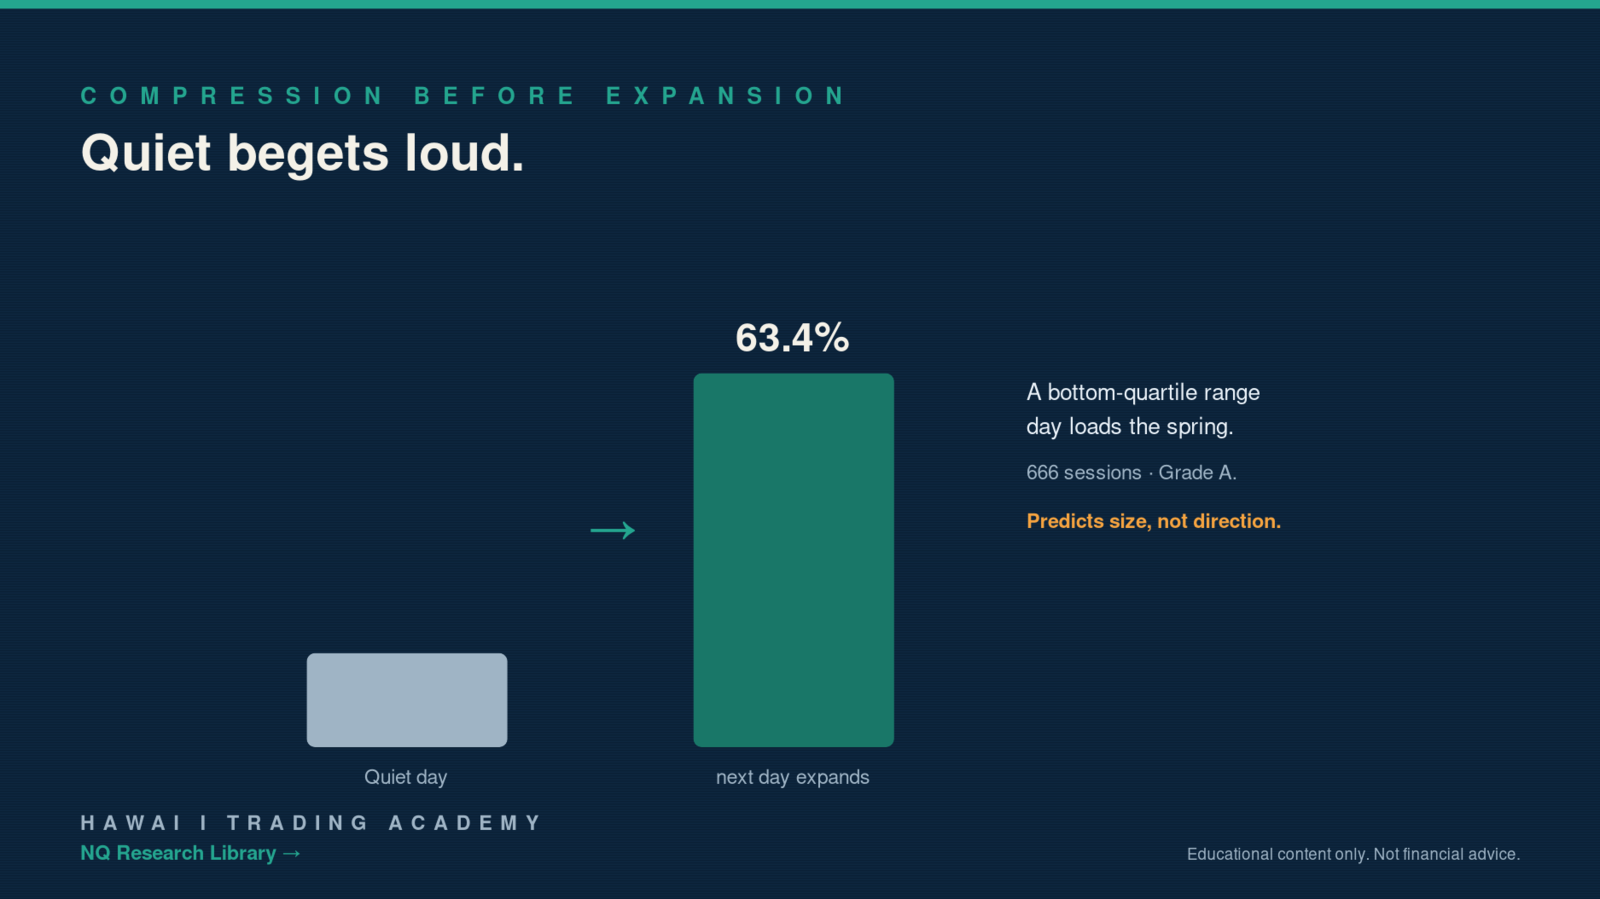
We took 666 bottom-quartile range days, the quietest sessions. The next regular session expanded 63.4% of the time. Significant in every session window we checked.
Why Quiet Loads the Spring
Volatility clusters and mean-reverts in size. A tight day is the market coiling. It rarely stays coiled. The energy that did not come out today tends to show up tomorrow.
This is one of the cleaner patterns in the whole library. It replicated across discovery, validation, and holdout. Grade A.
What It Actually Tells You
Here is the honest boundary. It predicts size, not direction. A quiet day says tomorrow is more likely to be a mover. It does not say up or down. That is a huge difference for how you plan.
What you do with it is prep. After a compressed day, widen your expectations. Do not get caught sizing for another dead session when the range is about to double.
The full com...
Downside Shocks Hit Harder and Linger Longer
Up moves and down moves are not mirror images. Anyone who traded a real selloff knows it in their gut. We put a number on it for NQ.
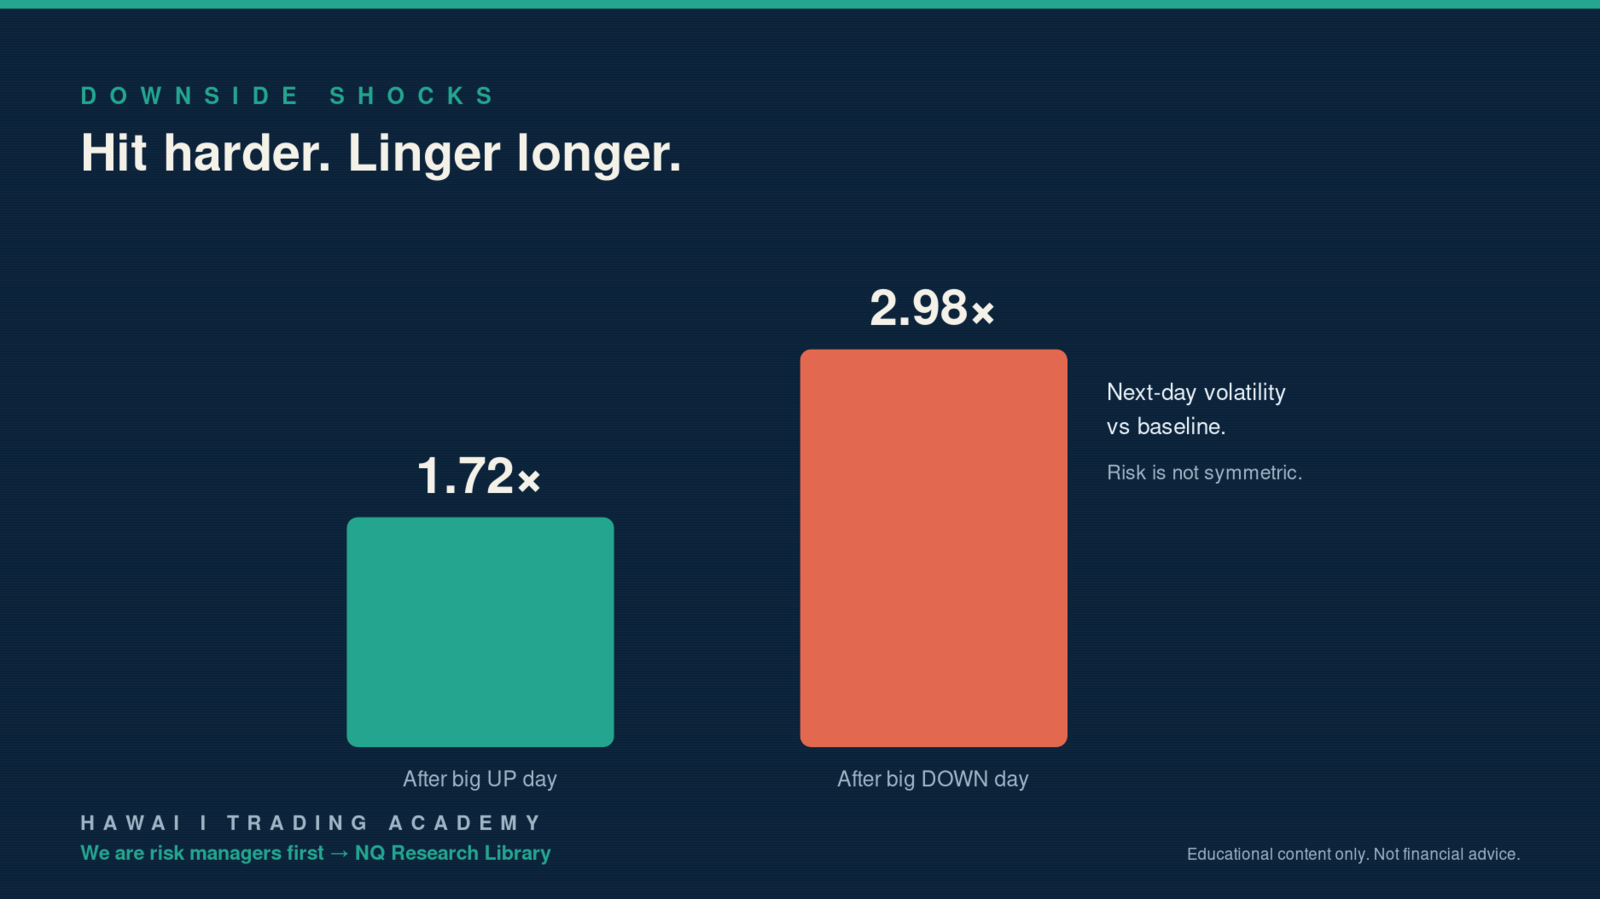
We compared the largest down days to the largest up days. After a big down day, next-day volatility ran a median 2.98 times baseline. After a comparably big up day, only 1.72 times.
Fear Moves Faster Than Greed
Selloffs feed on themselves. Margin calls, forced selling, stops cascading. The tape stays wild the day after, and often longer. Rallies tend to be calmer and slower.
233 large-down days and 198 large-up days went into this. It is not a fluke of one crash. It is the shape of the market.
Why This Is a Risk Rule, Not a Trade
This will not tell you to buy or sell. It tells you the environment. The day after a big drop is a high-volatility environment whether you are long, short, or flat. That is when position sizing saves accounts.
Size the same after a selloff as you do on a calm day and you are taking on far more real risk than your positio...